
Mortgages will cost more than 600 euros a year for every 100,000 euros borrowed
According to ASUFIN, the euro will be 3.2% in September and will make mortgages at variable rates more expensive.


Variable-rate mortgages could rise significantly if expectations of the Eurybor's evolution are met, according to estimates by the Financial Users Association (ASUFIN), which estimates that the Eurybor could close at 3.2% in Septemberfollowing the European Central Bank (ECB) 's decision to raise interest rates by 25 basis points.
The increase would have adirect impact on mortgage fees reviewed on the basis of the Eurybor. According to ASUFIN, a mortgage of 100,000 euros, contracted for 25 years, would go from paying more than 483 euros to almost 539 euros per month.
This would mean an additional EUR 55 per month, or EUR 668 per year.
A loan of EUR 100 000 for 30 years would increase the quota from almost EUR 431 to EUR 489 per month, with an increase of around EUR 58 per month and almost EUR 700 per year.
4.20% interest rate from
ASUFIN has taken into account the 4.20% interest rate in its calculations, which it estimates will reach 3.2% in September and an additional 1% differential.
It compares the estimate to the September 2025 Eurybor, when it was 2.172% , in which case it also adds a 1% differential.
ASUFIN recalls that most variable-rate mortgages are reviewed every six or twelve months, depending on the evolution of theEuribor, so the increase in the index is reflected in the quota in the next review, although the exact impact depends on the conditions of each loan.
Recommendations for lowering the quota
One option is to renegotiate the terms of the mortgage with the bank in order to avoid an increase in monthly payments, and to request subrogation in the transfer of the loan to another bank, or to change the mortgage at variable rates to fixed or mixed rates.
Another option is to repaythe mortgage in advance in order to reduce the capital owed, while extending the term of the loan may reduce the monthly fee, but it means paying interest for longer, thereby increasing the total cost of the mortgage.
ASUFIN recommends comparing these options, as depending on the characteristics of each loan, the economic conditions and effects may be different.
You might like
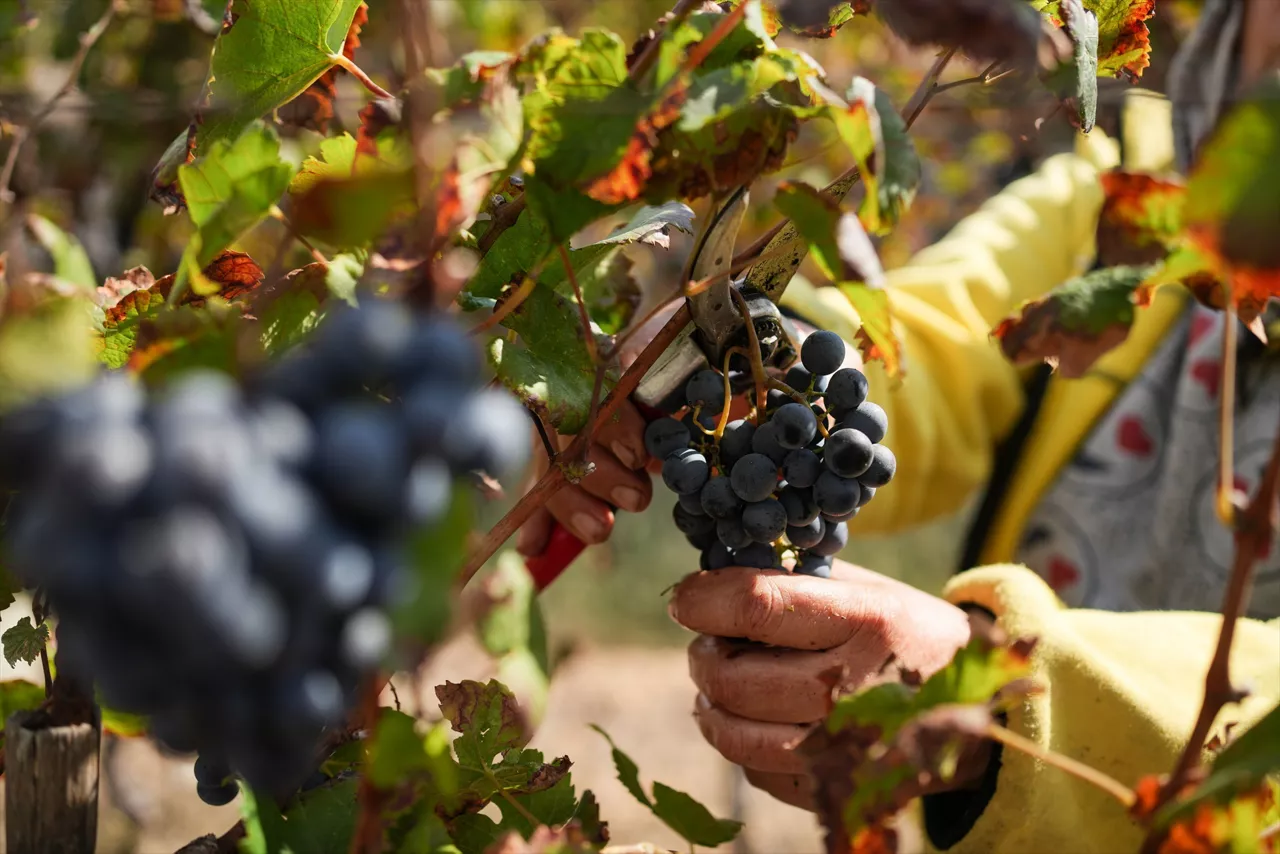
The earliest vintage in history in Rioja Alavesa has been produced by climate change
Temperatures have been high and it has barely rained, which has meant that there has been hardly any fungal disease and that the quality of the grapes is "excellent". On the other hand, weather conditions have raised the alcoholic graduation, which "must be compensated in the cellar," they say.

An incident with batteries paralyzes the production of electric cars at Volkswagen Navarra
The supplier has solved the problem and is producing normally, so Volkswagen Navarra hopes to resume activity "immediately."

CCOO explains to Pradales its "precautions" in the face of various competences affecting a large number of workers
The Secretary General of CCOO Euskadi, Santiago Martínez, has defended before the lehendakari the full compliance with the Gernika Statute, although he has been "cautious" about certain transfers of competences, such as those relating to FOGASA or pensions, which affect many workers and which, he stressed, "must be done well".

UGT urges Pradales to allocate business profits to wages
The chairman of the management committee of UGT Euskadi, José Manuel "Tximi" López, has defended before the lehendakari, Imanol Pradales, the need for the profits of large companies to be reflected in the wages of workers and has asked the Basque Government to mediate so that the Basque employers can sit down and negotiate the interprofessional minimum wage through agreements.

Ondarroa Trawl Fleet: "Going out to sea with diesel prices is a loss of money"
Professional diesel has increased by 227% since February, and the Ondarroa High Fishing Producers Association has reported that this increase must be assumed by fishermen because the wholesaler sets the purchase price for fish.
The Provincial Council of Bizkaia approved the draft new tax rule with the votes of the PNV and the abstention of the PSE-EE
According to the foral institution, PNV and PSE-EE have reached a "minimal agreement" and the text will be forwarded to the General Meetings to begin its parliamentary proceedings.
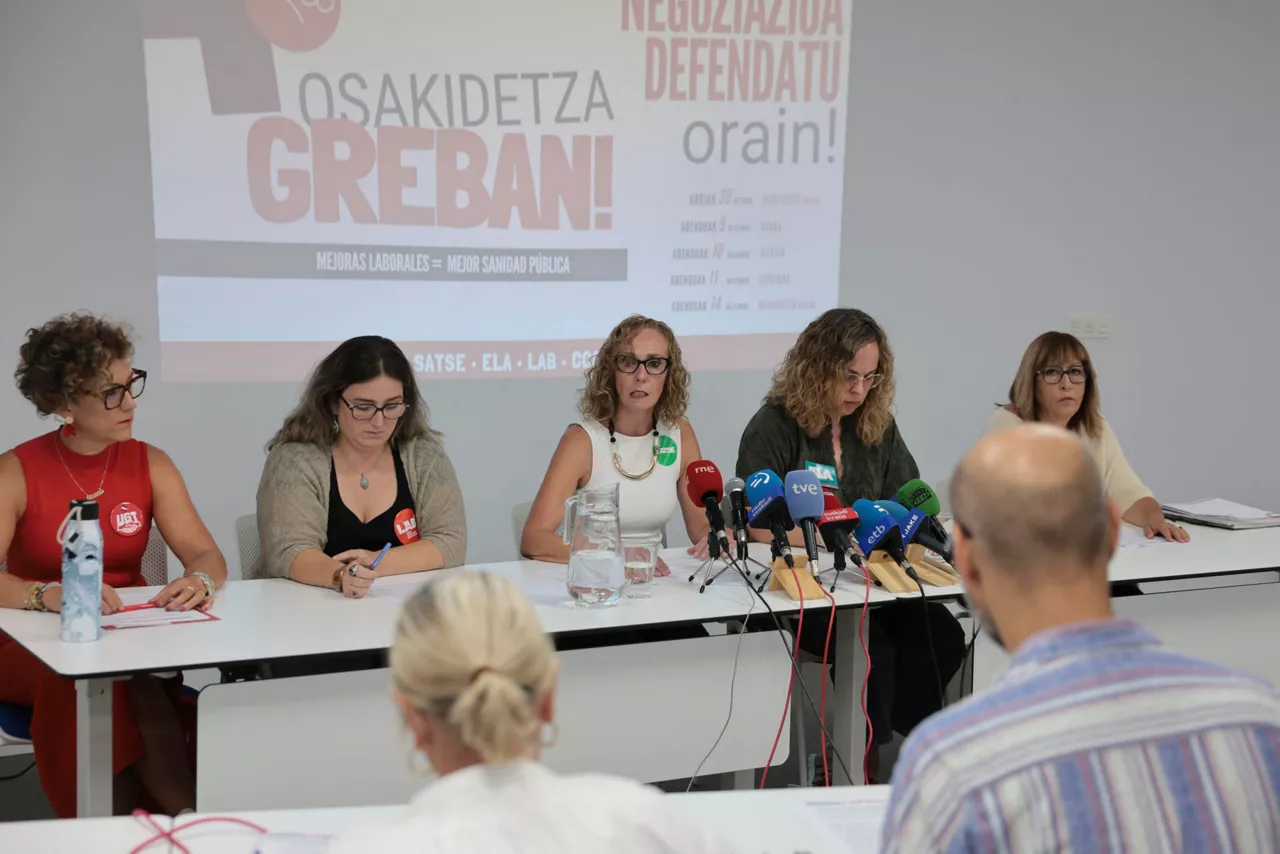
"The Basque Government has no will to improve the situation of all groups"
SATSE, ELA, LAB, CCOO and UGT have announced five strike days between October and December to demand better working conditions for all Osakidetza groups and a "real negotiation with real content."

More than 2,000 people have enrolled in the Osakidetza Life program to prevent suicide
The Department of Health has launched new initiatives in the Basque Country in the face of suicide, such as online training for families and teachers in early detection of warning signs, while the follow-up protocol for new suicide attempts has already served about 4,000 people.

Osakidetza unions call for five strike days between October and December
All Osakidetza workers are called to strike on 30 October and 14 December, 9 December in Álava, 10 December in Bizkaia and 11 December in Gipuzkoa.